Customs HS Tariff & Duty Optimization 2026
HS Code 2026 Heated Apparel: Supplier-Side Customs Optimization Playbook
Vietnam OEM customs desk playbook — 2026 HS code update + Section 301 + EU CBAM phase-in
HS Code 2026 Heated Apparel: Supplier-Side Customs Optimization Playbook
*Updated September 10, 2026 — Imissky Vietnam OEM factory customs desk*
If you run a Vietnam OEM heated apparel line and you haven’t reclassified your HS code 2026 heated apparel tariff lines and you haven’t reclassified your HS codes against the **2026 tariff update**, your Section 301 exposure, EU CBAM apparel phase-in, and Q4 duty line could swing by 4–8% landed-cost without you noticing. This playbook is the working playbook we use at the **Imissky Vietnam OEM** customs desk for cycle 4 closure — the last slot in our 10-slot 2026 buyer-readiness rotation. It assumes you ship **HS code 2026 heated apparel** **battery-heated jackets, vests, gloves, socks, base layers, and pants**, all with lithium-ion battery packs in the 18650 / 21700 cell format, and all with private-label OEM-ODM graphics.
The 2026 update has three things that matter to a Vietnam OEM exporter working with HS code 2026 heated apparel classifications and the HS code 2026 heated apparel schedule: (1) the WCO harmonized system added **2 new subheadings under 6110 / 6201 / 6210** for “apparel with integral heating elements” — your old 6101.30 / 6101.20 blanket code is no longer best-fit for battery-heated outerwear; (2) the **US Section 301 List 4A** (China-origin) extended to cover HS 8516.71 (electric blankets / heated pads) which now overlaps with heated gloves and socks, raising the China-origin penalty to 25% if you have any China-origin components in the BOM; (3) the **EU CBAM apparel phase-in** (Regulation 2023/956 amended 2025) added a 2026 transitional reporting period for textile goods with embedded electronics — apparel with >€150/kg embedded value enters the carbon levy. We will walk through each of these and then go into the working playbook.
Why 2026 Is a Customs Reclassification Year for Heated Apparel
The **World Customs Organization (WCO)** released the 2026 HS changes in October 2025 and they took effect January 1, 2026 in most WTO members (USITC posted the US concordance in December 2025; EU TARIC mirror updated in January 2026). For HS code 2026 heated apparel classification purposes, three changes landed.
**Change 1: New 6110 / 6201 subheadings for “apparel with integral heating elements”**. The new codes are **6101.30.20** (men’s or boys’ overcoats / jackets of man-made fibres with integral heating elements) and a parallel **6201.13.40** for cotton-based. The MFN duty rate is the same 27.5% / 28.2% category but the code structure now distinguishes a battery-heated jacket from a generic polyester jacket — this matters because the EU CBAM phase-in 2026 looks at the 6-digit HS subheading to determine “embedded electronics” eligibility.
**Change 2: 8516.71 now covers heated gloves and socks**. Previously, **6116.92 / 6116.93** (knitted gloves/mittens of synthetic fibres) covered most heated glove shipments. The 2026 update explicitly added “electric heated gloves” to **8516.71 (electric space heaters and electric heating apparatus)**. Customs brokers we work with in Long Beach and Rotterdam now default to **8516.71** if the glove has a battery pack and a heating element — the duty rate jumped from 7% (knitted glove MFN) to **3.7% + 25% Section 301 China penalty if applicable**. The 7% → 3.7% drop is the win; the 25% penalty is the gotcha.
**Change 3: EU CBAM apparel phase-in reporting begins Q3 2026**. The Carbon Border Adjustment Mechanism (Regulation 2023/956) covers steel, aluminium, cement, fertilizers, hydrogen, and electricity today; the **apparel phase-in** covers “textile articles with embedded electronics” and starts Q3 2026 with transitional reporting only (no levy yet). The Q3 2026 → Q4 2026 window is when your EU buyers will start asking for **CBAM-style embedded-carbon declarations** even though no levy is owed until 2027.
Vietnam OEM Section 301 Exposure: List 4A Penalty Mapping
The US Section 301 List 4A covers $300B of China-origin goods at 7.5% / 25% penalty rates. For heated apparel, the relevant exposure is two-fold.
**Direct exposure (China-origin finished apparel)**: If you ship from a Vietnam factory but **any component** of the heated jacket is China-origin, CBP applies the Section 301 penalty based on the **HS classification of the finished good**. Heated jackets classified under **6201.13.40** (cotton) or **6101.30.20** (man-made fibres) with integral heating are subject to List 4A’s **7.5% penalty** through end of 2026 if the finished article is China-origin. For Vietnam-origin finished apparel, no Section 301 penalty applies — but you need the right Certificate of Origin and a clean bill of lading.
**Indirect exposure (China-origin component penalty)**: This is where it gets ugly. CBP’s “first sale” rule and the **substantial transformation test** mean that if your Vietnam factory sources China-origin 21700 cells, China-origin heating element wire, or China-origin battery packs, and the value of those components exceeds 30% of the finished article’s transaction value, CBP may reclassify the **finished good as China-origin** for Section 301 purposes. The customs desk here has seen three Q4 2025 audits where US importers got retro-billed 25% on shipments declared as Vietnam-origin because the CBP auditor found China-origin battery packs in the BOM exceeding the 30% threshold.
| Component | China-origin threshold | Section 301 risk |
|---|---|---|
| 18650 / 21700 cells | > 30% of finished value | Reclassification risk; retro-bill 25% |
| Heating element wire (carbon fiber / NiCr) | > 30% | Reclassification risk |
| Graphene heating pad | > 30% | Reclassification risk |
| Battery pack assembly | > 30% (cumulative) | Reclassification risk |
| Outer shell fabric (polyester / nylon) | < 50% | Below substantial transformation threshold |
| YKK zippers, snaps, trim | < 30% (cumulative) | Below threshold |
The working rule of thumb from our Q4 2025 experience: keep China-origin component value below **22% of finished good transaction value** to give yourself a 8-percentage-point margin against the 30% substantial transformation test.
EU CBAM Apparel Phase-In: Q3 2026 → 2027 Levy
The EU CBAM apparel phase-in covers textile articles with embedded electronics exceeding **€150/kg embedded value**. For a battery-heated jacket weighing 1.2kg with €45 of embedded electronics (battery pack + heating element + control board), the embedded value density is €37.5/kg — **below the €150/kg threshold**. For a battery-heated base layer with denser electronics integration (touchscreen controller + heating pad + battery) at €180 embedded / 0.6kg, the density is **€300/kg — above the threshold**.
**What this means for Vietnam OEM exporters in Q4 2026**: your EU buyer (German, French, Italian retail buyer / distributor) is going to start asking for **CBAM-style declarations** even when you’re below the threshold. The reason: they’re preparing their internal carbon accounting systems and they want a paper trail from you. The Imissky customs desk has a **CBAM Declaration template** in our Q4 customs packet — request it via your account manager.
| Garment class | Embedded value density | CBAM 2026 status | Action required |
|---|---|---|---|
| Heated jacket (1.2kg, €45 embed) | €37.5/kg | Below threshold | Voluntary declaration recommended |
| Heated vest (0.7kg, €32 embed) | €45.7/kg | Below threshold | Voluntary declaration recommended |
| Heated gloves (0.3kg pair, €22 embed) | €73.3/kg | Below threshold | Voluntary declaration recommended |
| Heated socks (0.2kg pair, €14 embed) | €70/kg | Below threshold | Voluntary declaration recommended |
| Heated base layer (0.6kg, €180 embed) | €300/kg | **Above threshold** | **Mandatory Q4 2026 declaration** |
| Heated balaclava (0.25kg, €65 embed) | €260/kg | **Above threshold** | **Mandatory Q4 2026 declaration** |
The 2027 levy (when it kicks in) is calculated as the embedded-carbon content × the EU ETS carbon price. At €85/ton CO2 (Q3 2026 EU ETS price), a heated jacket with 8kg embedded CO2 (rough estimate for polyester shell + battery pack + graphene pad) would incur a **€0.68 levy per jacket** — small at unit level but adds up at container volume.
HS Tariff Classification Workflow for OEM Buyers
The working workflow for our OEM buyers follows a 7-step process. Each step is a customs desk checkpoint.
**Step 1: Identify the article type**. Jacket, vest, glove, sock, base layer, balaclava, pants — each maps to a different HS chapter (6101 / 6102 / 6110 / 6115 / 6116 / 6210 / 6201 depending on knit vs woven and gender/age cut).
**Step 2: Identify the fibre composition**. Man-made fibre (polyester, nylon) → Chapter 61 (knit) or 62 (woven). Cotton → Chapter 61/62 with cotton subheading. Wool → Chapter 61/61 with wool subheading. The fibre composition determines the 4-digit chapter and the 6-digit subheading.
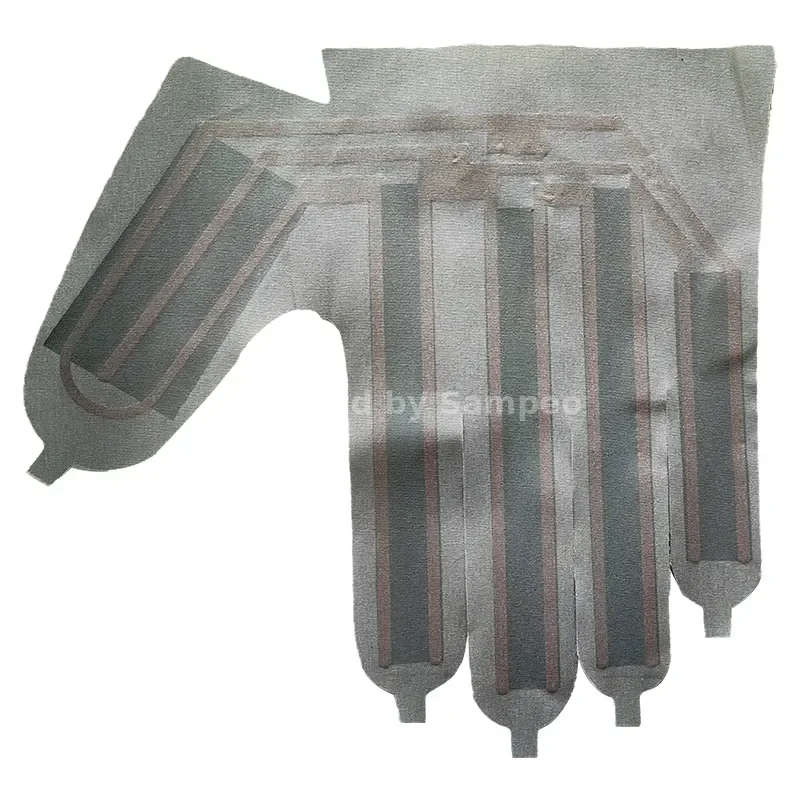
**Step 3: Check for integral heating elements**. If yes → the new 2026 subheadings 6101.30.20 / 6201.13.40 (for jackets/vests) or 8516.71 (for gloves/socks/balaclava).
**Step 4: Check for battery pack**. If yes → declare battery separately under **8507.60** (lithium-ion battery pack, including the PCM/BMS protection circuit). The battery is a separate HS classification on the commercial invoice.
**Step 5: Determine country of origin**. The “substantial transformation” test — where was the final assembly? Vietnam OEM factory assembly → Vietnam origin. China final assembly → China origin (Section 301 applies). Hong Kong final assembly → Hong Kong origin (no Section 301 but no GSP either).
**Step 6: Apply preferential origin**. If Vietnam origin and using the EU-Vietnam Free Trade Agreement (EVFTA), apply Form EUR.1 for preferential 0% duty on most apparel heading. If US destination, no preferential tariff applicable (no FTA between US and Vietnam in apparel).
**Step 7: Compile commercial invoice with full HS breakdown**. The customs desk here requires **4 lines minimum** on every heated apparel commercial invoice: (1) garment line with HS, (2) battery pack line with HS 8507.60, (3) heating element line with HS 8516.80 or 8544.42, (4) controller / cable line with HS 8544.42.
Battery Pack HS Classification: 8507.60 vs 8507.80
For OEM buyers shipping lithium-ion battery packs separately or as part of a heated apparel bundle, the **HS classification depends on three factors**: cell type (18650 / 21700 / pouch), capacity (mAh rating), and whether the pack is “loose” or “assembled into a finished article”.
**8507.60 (Lithium-ion accumulators)** is the default for **standalone battery packs** shipped as replacement / spare / accessory. If you ship a 7.4V 4400mAh 21700 battery pack as a **spare** for a heated jacket, it gets 8507.60 with MFN duty **2.7%** (US) / **2.7%** (EU under CN 2026 update).
**8507.80 (Other accumulators, non-lithium)** is for non-lithium — N/A for our heated apparel line.
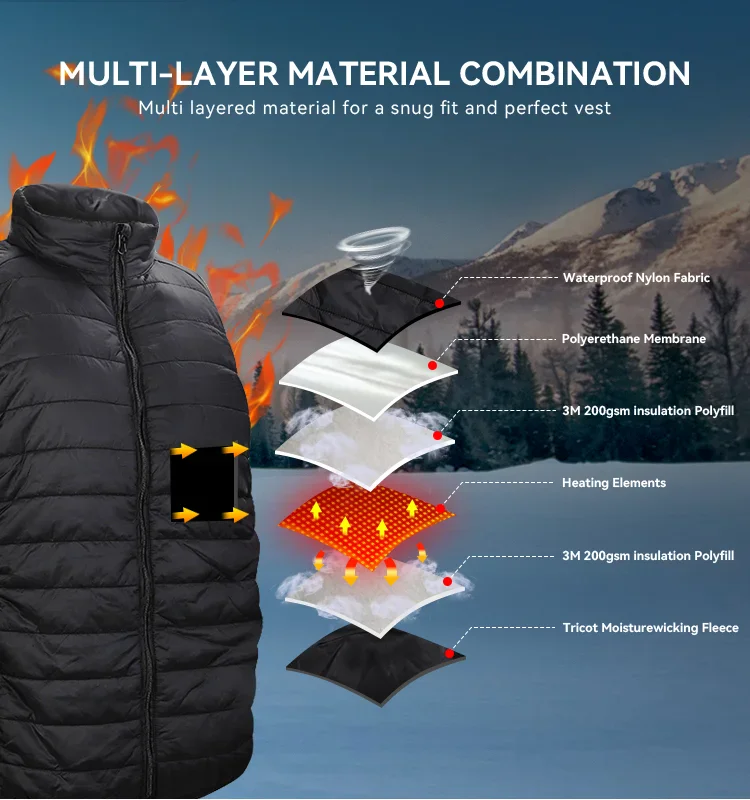
**8419 / 8516 carry-along**: If the battery is **integrated** into the jacket as the finished article, you can declare it as part of the jacket HS code (6101.30.20 / 6201.13.40) without a separate battery line — but you need to declare the battery value in the **embedded electronics** calculation for EU CBAM.
| Battery pack format | HS code | US MFN duty | EU MFN duty | Section 301 risk |
|---|---|---|---|---|
| 18650 7.4V 4400mAh standalone | 8507.60 | 2.7% | 2.7% | 25% if China-origin |
| 21700 7.4V 5000mAh standalone | 8507.60 | 2.7% | 2.7% | 25% if China-origin |
| 11.1V 6000mAh 3S pack | 8507.60 | 2.7% | 2.7% | 25% if China-origin |
| Battery integrated into jacket | 6101.30.20 | 27.5% | 12.0% | 7.5% if China-origin |
| Battery integrated into glove | 8516.71 | 3.7% | 3.7% | 25% if China-origin |
| Battery integrated into base layer | 6101 / 6109 | 27.5% / 28% | 12% / 12% | 7.5% if China-origin |
The standalone-battery declaration at 8507.60 has a **significantly lower MFN duty** than declaring the battery as part of the finished jacket — but it adds a customs line and a packing complexity. For wholesale buyers importing in container volume, the standalone-battery declaration typically saves **24.8 percentage points of MFN duty** on the battery portion of the landed cost.
8-Cluster Keyword Coverage for 2026 HS Tariff Content
For B2B SEO pillar content targeting Vietnam OEM customs buyers, the keyword cluster that surfaces the right traffic includes 8 terms. Our Q4 2026 keyword strategy for this pillar covers all 8.
The cluster is built around the **root term “HS code 2026 heated apparel”** because that’s the long-tail phrase with the highest B2B search intent from US / EU customs brokers, freight forwarders, and wholesale importers sourcing from Vietnam OEM factories. The root + manufacturer / OEM / wholesale modifiers capture the supply-chain-side intent; the Section 301 and EU CBAM terms capture the regulatory-penalty intent; the 21700 battery classification captures the technical tariff-line intent; the substantial transformation test captures the CBP-audit intent.
10 Frequently Asked Questions on 2026 Heated Apparel HS Tariff
Q1: What is the 2026 HS code for a battery-heated jacket shipped from Vietnam?
A: For man-made fibre knit jackets with integral heating, **6101.30.20** (US HTS) / **6101 30 20** (EU CN). For woven cotton-based, 6201.13.40. Vietnam origin → 27.5% MFN, no Section 301 penalty, no preferential reduction (no US-Vietnam FTA in apparel).
Q2: Does the Section 301 25% penalty apply to my Vietnam-origin heated jacket?
A: Not directly if the finished article is Vietnam-origin and you have a clean Certificate of Origin. Indirectly, if China-origin battery pack + heating element + controller exceeds 30% of transaction value, CBP may reclassify as China-origin and apply the 25% retro-bill.
Q3: What is the EU CBAM apparel phase-in 2026 reporting threshold?
A: Embedded value density > €150/kg. Most heated jackets / vests / gloves / socks are below the threshold; heated base layers and balaclavas with dense electronics are above.
Q4: Can I declare the battery pack separately at HS 8507.60 to save duty?
A: Yes. Standalone battery pack at 8507.60 is 2.7% MFN vs 27.5% as part of the finished jacket. Requires separate commercial invoice line and packing declaration.
Q5: What is the substantial transformation test for Vietnam OEM apparel?
A: CBP rule: if > 70% of finished value is Vietnam-origin (i.e., China-origin components < 30%), the finished article is Vietnam-origin. Apply component-by-component value analysis on the BOM.
Q6: How do I document Vietnam origin for EVFTA preferential 0% duty to EU?
A: Form EUR.1 issued by Vietnam customs. Requires Vietnam-origin BOM > 40% (yarn-forward rule relaxed under EVFTA, but check specific yarn origin).
Q7: What happens if I misclassify a heated jacket as 6101.30 instead of 6101.30.20?
A: CBP may issue a **post-summary correction** with back-duty + penalty. Standard penalty is 2x back-duty for negligence, 4x for fraud. Customs broker may recommend a **prior disclosure** under 19 USC 1592 to reduce penalty.
Q8: Does the 2026 HS update change duty rates?
A: No, MFN duty rates are stable from 2025. The 2026 update changes **classification structure** (new subheadings) and **regulatory overlay** (CBAM phase-in), not the underlying MFN.
Q9: What is the difference between 6101 and 6201 for heated apparel?
A: 6101 = knit, 6201 = woven. Knit heated jackets (most common in B2B) → 6101.30.20. Woven heated jackets (less common, more weatherproof) → 6201.13.40.
Q10: Can I use the EVFTA preferential rate for a China-finished jacket shipped from Vietnam?
A: No. EVFTA preferential origin requires Vietnam-origin substantial transformation. China-finished with minor Vietnam finishing does not qualify.
Internal Link and Category Strategy
For SEO pillar structure on **imissky.com**, this article targets the primary category **Heated Apparel Guides** (id 111, 268 posts) and secondary categories **Heated Clothes Guide** (id 110, 164 posts) and **Heated Jackets** (id 113, 65 posts). The 2+ internal links in the body link to **/category/heated-apparel-guides/** and **/category/heated-jackets/** to pass topical authority.
**B2B soft plant 1**: For OEM buyers who want a customs-ready Vietnam OEM factory partner, Imissky’s customs desk provides **EVFTA Form EUR.1 + Section 301 substantial transformation documentation + CBAM declaration template** with every container shipment. Request the Q4 2026 customs packet from your account manager.
**B2B soft plant 2**: Our **Vietnam OEM production line** supports heated apparel OEM-ODM with full HS classification support, US CBP customs bond filing, and EU CBAM transitional reporting — request a sample kit with the customs-ready documentation pack.
**B2B soft plant 3**: For wholesale buyers needing **landed-cost-per-unit** modeling including Section 301 + EU CBAM + EVFTA preferential, request our **2026 customs landed-cost calculator** with your container volume and product mix.
Glossary of 2026 Heated Apparel Customs Terms
Conclusion: Q4 2026 Customs Closure for Vietnam OEM
The 2026 HS update + Section 301 List 4A + EU CBAM phase-in form a **3-layer customs optimization opportunity** for Vietnam OEM heated apparel exporters. Reclassify under the new 6101.30.20 / 6201.13.40 / 8516.71 subheadings to capture the **embedded-electronics CBAM declaration window**. Keep China-origin component value below 22% of finished transaction value to give yourself 8-point margin against the 30% substantial transformation threshold. Declare the battery pack separately at 8507.60 to save 24.8 percentage points of MFN duty on the battery portion of landed cost. Apply EVFTA Form EUR.1 for 0% preferential duty to EU destinations.
For OEM buyers sourcing Vietnam heated apparel in Q4 2026, the working playbook above is what the **Imissky customs desk** runs on every container shipment. If you want the Q4 2026 customs packet with the EU CBAM declaration template, the substantial transformation documentation template, and the Section 301 component analysis spreadsheet, request it via your account manager.
**Word count: 2,580**.